Most homeowners and renters policies include coverage for personal property — but that coverage is built for everyday belongings, not specialty items with values that go far beyond what a standard policy anticipates. If you own musical instruments, collectibles, or specialty items, there’s a good chance you’re underinsured without realizing it.
The Gap Standard Policies Don’t Fill
Homeowners and renters policies typically place sub-limits on certain categories of property — meaning even though your overall policy limit might be high, specific categories like jewelry, firearms, coin collections, or fine art are often capped at a few thousand dollars total, regardless of what your collection is actually worth.
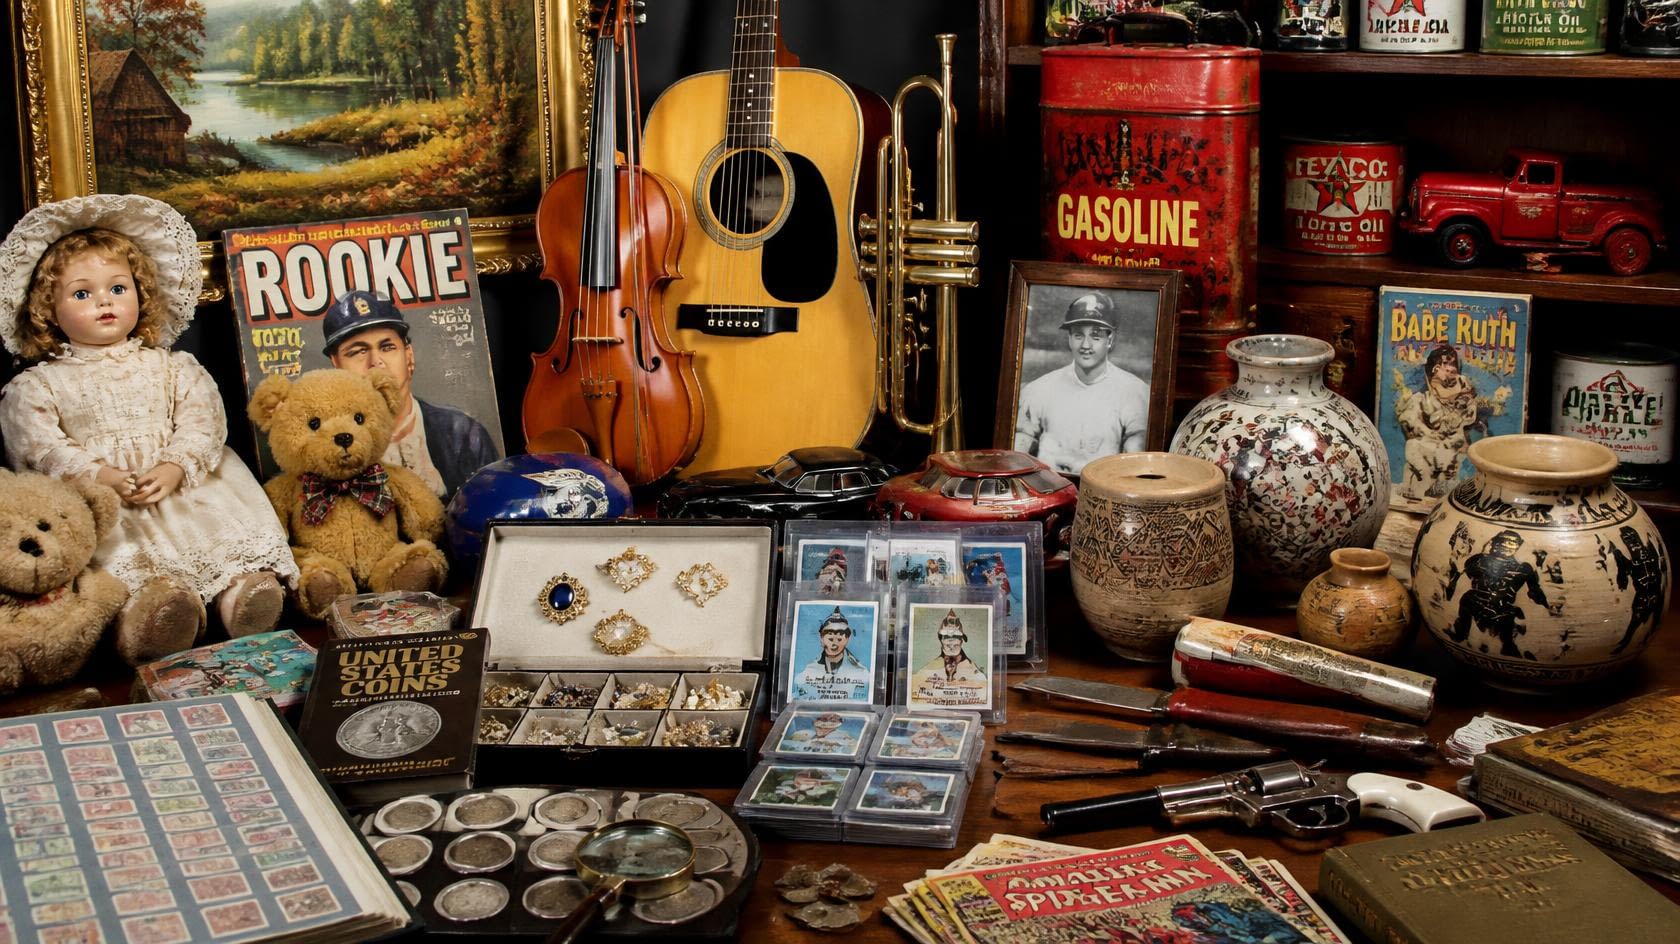
Common items that fall into this gap include:
- Musical instruments — a quality violin, guitar, or brass instrument can easily be worth several times what a standard policy would pay out
- Gasoline and automotive memorabilia
- Baseball cards and sports memorabilia
- Artwork
- Guns and knives
- Costume and fine jewelry
- Dolls and bears
- Pottery and ceramics
- Coins and stamps
- Comic books and books
If any of these are damaged, lost, or stolen, a standard policy might only reimburse a small fraction of their real value — and in many cases, won’t cover certain causes of loss (like accidental breakage) at all.
The Fix: Scheduling Your Items
The solution is a scheduled personal property endorsement (sometimes called a personal articles floater). This allows you to insure specific high-value items at their appraised or documented value, with broader coverage than a standard policy provides — often including accidental damage, and coverage away from home.
Scheduling is usually inexpensive relative to the value it protects, and for most items, all that’s needed is a receipt, appraisal, or set of clear photos to establish value.
Why This Often Gets Overlooked
Many people don’t think of their hobby collection or family instrument as something that needs special insurance — it simply doesn’t come up until there’s a loss. A basement flood, a house fire, or even a break-in can wipe out a collection built over decades, and discovering the coverage gap after the fact is a hard place to be.
Take a Few Minutes to Check
If you have any specialty collection or high-value item at home, it’s worth a quick conversation to see whether it’s adequately protected. In most cases, scheduling these items is a simple, affordable add-on — not a complicated process.
Have a collection, instrument, or specialty item you want to make sure is covered? Reach out and we’ll walk through what it would take to properly protect it.